Independent claim appraisal · All 53 counties
North Dakota Insurance Appraiser for hail, wind & winter claims that came up short
When the insurer accepts the claim but the check won’t cover the repair, North Dakota Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
- Your appointed appraiser
- Cold-climate scope & code items
- Homes, HOAs, farms & commercial
01Claim calendar
Four seasons, four kinds of claims
A North Dakota Insurance Appraiser sees the year in claim types. Knowing which season produced the damage shapes what to look for — and what the carrier may have missed.
Spring Mar–May
Snowmelt, ice jams and saturated ground. Sump failures, seepage and roof leaks from late-season ice dams.
Summer Jun–Aug
Peak hail and severe-storm season: shingles, siding, windows, metal buildings — plus straight-line winds and tornadoes.
Fall Sep–Nov
Dry, windy days raise grass-fire risk out west, and a race to finish repairs before freeze-up.
Winter Dec–Feb
Blizzards, frozen pipes, ice dams and heavy snow load on roofs and outbuildings.
02Why owners call
Why property owners bring in a North Dakota Insurance Appraiser
Most underpaid claims aren’t denied. They’re short: a missed roof slope, siding that can’t be matched, an ice barrier nobody priced, a basement scoped as “clean and dry.” A North Dakota Insurance Appraiser exists for that gap between “covered” and “paid in full.”
- We scope it from scratch. Our own inspection and measurements — never an edited copy of the carrier’s estimate.
- Defensible, not inflated. Numbers built to hold up in front of an umpire, which is what moves awards.
- Honest triage. If your claim needs an attorney or a supplement instead, you’ll hear that on the first call.
03Services
Claims a North Dakota Insurance Appraiser takes on
Eleven services built around one job: a valuation of your loss that holds up. Start with an estimate review, or bring us in once appraisal has been demanded.
 01
Appraisal Clause Appointment
Your named appraiser when you or your carrier invokes the appraisal clause on a disputed North Dakota property claim.
 02
Home & Condo Claim Appraisal
Independent valuation of disputed home insurance claims, from roof and siding to basements, interiors and detached garages.
 03
Commercial, HOA & Multifamily Appraisal
Appraisal and estimating for disputed claims on commercial buildings, associations, apartment complexes and mixed-use properties.
 04
Hail, Roof & Siding Appraisal
Line-by-line valuation of hail damage to roofs, siding, gutters, windows and soft metals across North Dakota.
 05
Wind, Derecho & Tornado Appraisal
Appraisal of disputed straight-line wind, derecho and tornado claims, from lifted shingles to destroyed buildings.
 06
Water & Burst Pipe Appraisal
Appraisal of disputed water claims from burst or frozen pipes, appliance leaks and sump or sewer backups.
 07
Fire, Smoke & Grass Fire Appraisal
Appraisal of disputed fire, smoke and soot claims, including grass fire and wildfire exposure in western North Dakota.
 08
Freeze, Ice Dam & Snow Load Appraisal
Appraisal for frozen pipe bursts, ice dam leaks and snow-load roof damage or collapse, built for North Dakota winters.
 09
Farm & Ranch Building Appraisal
Appraisal of disputed claims on pole barns, Quonsets, steel buildings, shops, machine sheds and older barns.
04The route
From disagreement to signed award
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here’s the route North Dakota Insurance Appraiser follows on a typical file.
- 1
Define exactly what’s disputed
Confirm that the dispute is about the amount of loss, not coverage, and list exactly which items and dollar figures are contested.
- 2
Written appraisal demand
Send a written demand that invokes the appraisal clause, cites the policy and claim number, and follows any notice rules in the policy.
- 3
Both appraisers are appointed
The policyholder and the insurer each select a competent, disinterested appraiser within the window the policy sets.
- 4
Umpire selection
The two appraisers try to agree on a neutral umpire, and if they cannot, either side may ask a court of record to appoint one.
- 5
Inspection & independent estimates
Each appraiser inspects the property, reviews the claim file, and builds an independent, line-by-line estimate of the loss.
- 6
Appraiser negotiation
The appraisers compare estimates item by item, resolve what they can, and narrow the remaining differences to a short list.
- 7
Umpire review
Any items the appraisers cannot settle go to the umpire, who reviews both positions and decides each disputed amount.
- 8
Signed award & payment
An award signed by any two of the three panel members sets the amount of loss, and the insurer then pays under the policy terms.
05Quick math
Is your gap big enough to appraise?
Type in the two numbers you already have. A large difference is worth a conversation with a North Dakota Insurance Appraiser; a small one may close faster with a documented supplement.
The full award break-even calculator adds appraiser and umpire fees and shows your break-even point.
All seven free tools06Regions
Five claim climates in one state
Hail in the valley, river ice in the capital, wind in the oil patch, grass fire in the badlands. A North Dakota Insurance Appraiser has to know how each region’s weather shows up on a building — and in an estimate.
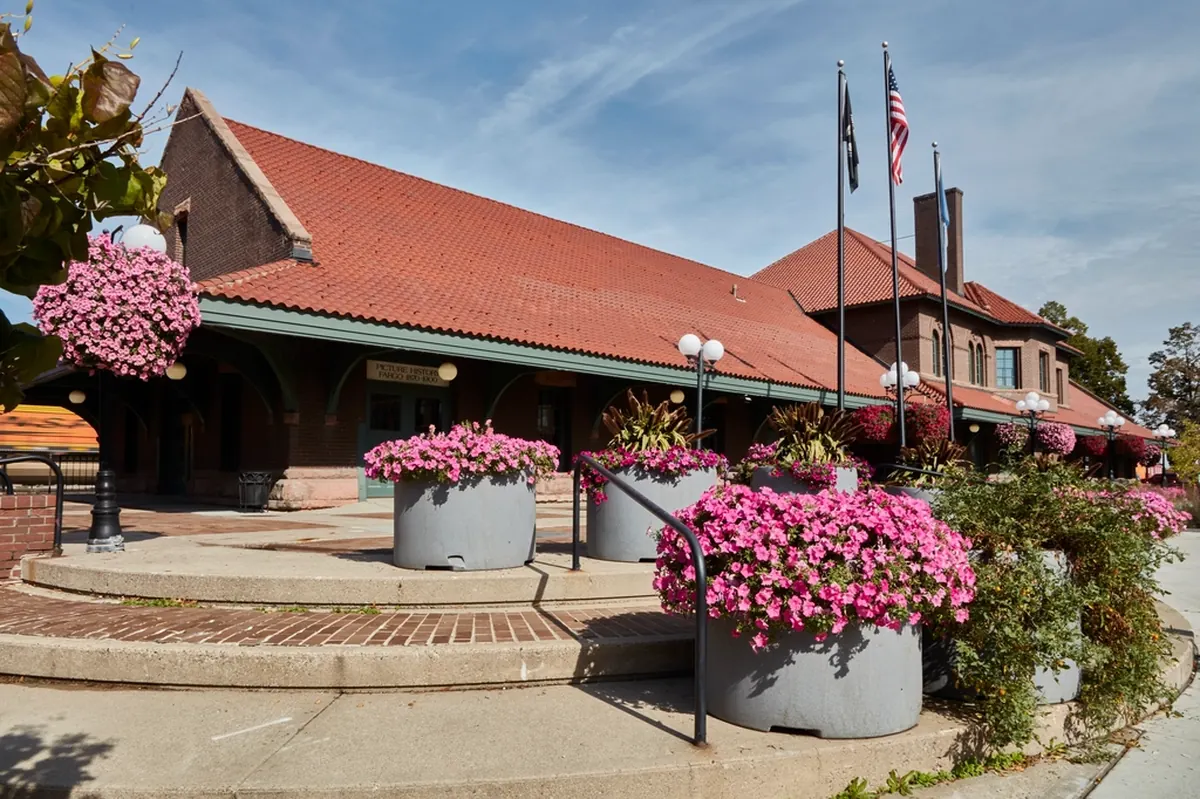
Red River Valley
Fargo · West Fargo · Grand Forks · Wahpeton
- Large hail
- Spring flooding
- Straight-line wind
- Basement water
The flattest, most populated corner of the state. Severe summer storms track straight across the valley, and snowmelt years bring sump, foundation and sewer-backup questions — many of them coverage issues, not appraisal issues.
Local pages: Fargo · West Fargo · Grand Forks · Wahpeton
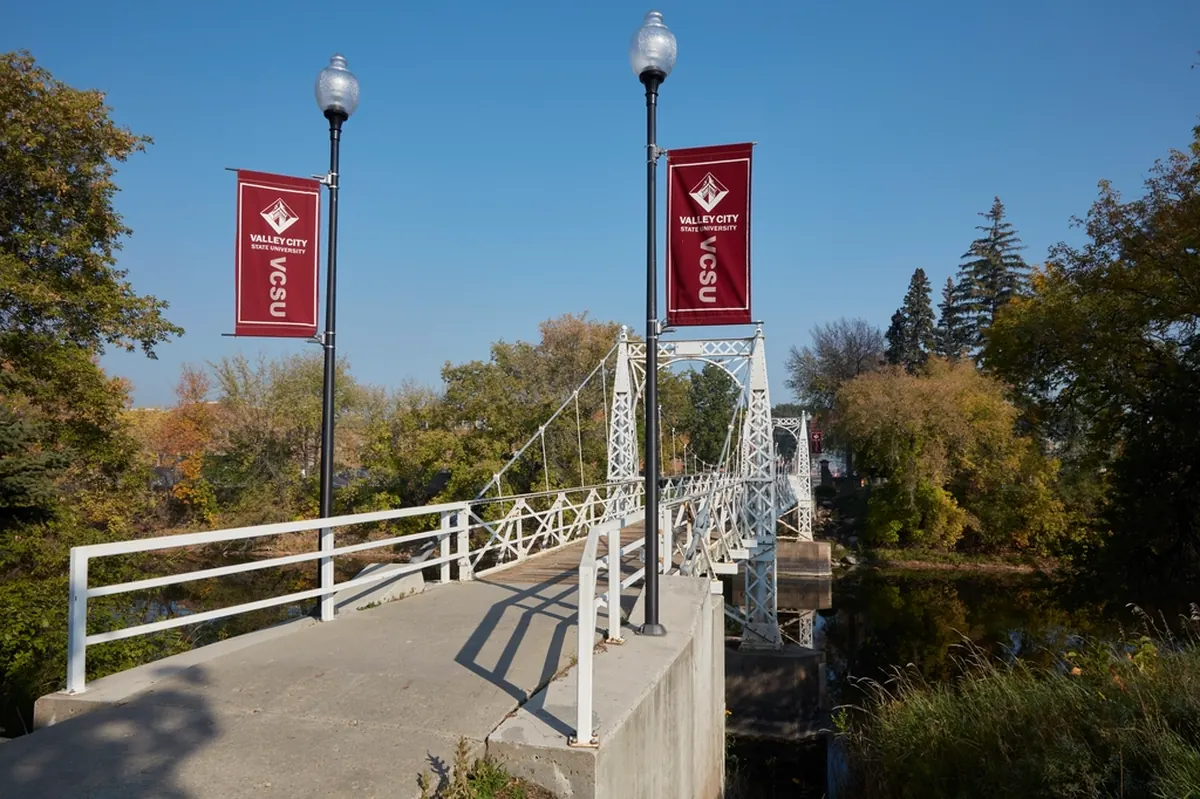
Lakes & Drift Prairie
Devils Lake · Jamestown · Valley City
- Hail on siding
- Ice dams
- Blizzards
- Wind
Small cities, farmsteads and lake homes spread across the prairie. Claims here often mix a house, a detached garage and an outbuilding or two — and adjusters can be days away after a big storm.
Local pages: Devils Lake · Jamestown · Valley City
Capital Corridor
Bismarck · Mandan
- Hail
- River ice & high water
- Snow load
- Fire
The capital region sits where the Heart River meets the Missouri River. Older homes near downtown, fast-growing subdivisions on the edges and a commercial core produce a wide mix of roof, siding and interior claims.
Southwest & Badlands
Dickinson · Medora
- Grass fire
- Wind
- Hail
- Extreme cold
Open rangeland, ranch buildings and oil-country towns. Dry, windy autumns raise grass-fire exposure, and long distances make careful documentation more important than ever.
Local pages: Dickinson
07Locations
North Dakota Insurance Appraiser near you
We work in every county. These are the communities where claims come from most often — each page covers local storms, housing and what tends to go wrong.
08Free tools
Seven free calculators from a North Dakota Insurance Appraiser
Run the numbers before you pick up the phone. Every tool works in your browser — nothing is stored or sent.
Open the tool libraryAward Break-Even Calculator
Size the disputed amount, test where an award might land and see your break-even point after fees.
ACVCalculatorTwo-Check Payout Calculator
List damaged items with age and life to estimate the first ACV check and the depreciation held back.
▲CalculatorRoof Area & Ice-Barrier Calculator
Turn a footprint into true roof squares, bundles and eave ice-barrier footage for a cold-climate roof.
%CalculatorHail Deductible Dollar Converter
Convert a percentage wind/hail deductible into dollars and see what a storm claim would actually pay.
◷PlannerPolicy Clock & Freeze-Up Planner
Map notice, proof-of-loss, holdback and suit dates from your date of loss, then export an .ics file.
✓ChecklistClaim File Strength Test
Twelve yes/no questions that score your claim file and build a to-do list before you invoke appraisal.
❄EstimatorSnow & Ice Roof Weight Estimator
Estimate pounds per square foot from snow depth, snow type and ice — and compare it with a design load.
09Right help
Which kind of help fits your claim?
Each solves a different problem, and picking the right one first saves time and fees. North Dakota Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
Party-appointed appraiser
Values the amount of loss
- Coverage accepted, number disputed
- Works inside the appraisal clause
- Binding award with two of three signatures
- Doesn’t decide coverage or bad faith
Licensed public adjuster
Manages and negotiates the claim
- Most useful early, from first notice
- Prepares and presents the claim
- Negotiated settlement
- Isn’t a lawyer
Insurance coverage lawyer
Handles legal disputes
- Denials and coverage fights
- Bad-faith and deadline questions
- Settlement or judgment
- Usually the costliest route
10Handbook
From the North Dakota claim handbook
Practical guides on policy language, documentation and winter losses, written by North Dakota Insurance Appraiser.
8 min readHow the Appraisal Clause Works in North Dakota Property Policies
A plain-language walk through the appraisal clause in North Dakota property policies, from the written demand to the signed award.
 7 min read
Hail Claim Documentation Checklist for North Dakota Homes
A step-by-step checklist for photographing and recording hail damage to roofs, siding, windows, and metal before memories and evidence fade.
 8 min read
Winter Claims in North Dakota: Ice Dams, Frozen Pipes, and Snow Load
What North Dakota homeowners should know about ice dam, frozen pipe, and snow load claims, including mitigation duties and how to document damage.
11Questions
Straight answers from a North Dakota Insurance Appraiser
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
What does a North Dakota Insurance Appraiser do?
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
How is that different from a public adjuster?
A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When should I call a North Dakota Insurance Appraiser?
When coverage is accepted, you have the carrier’s itemized estimate, and the gap between it and a contractor’s estimate is meaningful — generally more than about 10% or several thousand dollars.
Is the award binding?
On the amount of loss, generally yes, once two of the three panel members sign. That’s why the file should be complete before anyone demands appraisal.
What does it cost?
Each side usually pays its own appraiser and half of the umpire. Our fee is put in writing before work begins, and the first conversation is free.
Can winter damage wait until spring?
Report it now and protect the property; policy clocks keep running. Snow-covered roofs can be re-inspected after thaw, and that follow-up often matters for the scope.
12Start here
Put your numbers in front of a North Dakota Insurance Appraiser
Tell us what happened and what the carrier offered. You’ll get a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.
- Call or text+1 (844) 537-1427
- Emailinfo@northdakotainsuranceappraiser.com
- HoursMon–Fri, 8am–6pm CT
- CoverageAll 53 North Dakota counties